







Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Styles & brands we work with
- Kitchen remodeling
- Bathroom remodeling
- Home additions & ADU
- Roofing
- Windows & doors
- Driveway & pavers
- Fence
See the difference
 Before
 After
 Before
 After
 Before
 After
Do Impact Windows Lower Insurance in Inglewood, CA? The Honest Answer
Not through a standard discount, no. California homeowner policies aren’t structured around the wind-mitigation credits that give Florida homeowners 10-45% off for impact glazing, so you won’t find that line item on a typical Inglewood policy. The insurance benefit here is real but indirect: documented seismic-safety improvements, including laminated impact glass that reduces glass-fall hazard, can factor into how some carriers evaluate earthquake coverage endorsements. Call (833) 842-7204 and we’ll walk you through what documentation your carrier actually needs.
Inglewood makes this question sharper than most cities do. The housing stock is dominated by 1920s-1950s bungalows and stucco duplexes, and a large share of them have never had a permitted window upgrade. Meanwhile the 2021-2026 build-out around SoFi Stadium, the Intuit Dome, and the Kia Forum has pushed the City of Inglewood’s permit office into a much stricter posture on legacy unpermitted work. That matters for insurance in ways Florida’s hurricane-credit conversation never touches.
Key Takeaways
- California carriers don’t offer the standardized impact-window discount Florida carriers do. Anyone promising one on a standard basis is selling, not explaining.
- The realistic Inglewood angle is earthquake coverage endorsements and loss-mitigation credits tied to documented seismic improvements.
- No documentation, no credit. A permitted install with a dated City of Inglewood final inspection sign-off is the baseline.
- Your underwriter needs the NFRC rating and the frame spec of the installed unit. We hand over complete material documentation on every Andersen and Marvin install.
- The stronger case for impact windows here is seismic safety and 30-year durability. Insurance savings are a bonus, not the reason to buy.

Why the Florida Answer Doesn’t Transfer to Inglewood
Search “do impact windows lower insurance” and the top results are almost all Florida-based. That’s because Florida’s insurance market is built around hurricane risk, and its carriers are required to recognize wind-mitigation features through a formal inspection and credit process. Impact glazing is one of the features on that list, so the discount is real and predictable there.
California’s market doesn’t work that way. Our dominant peril isn’t wind, it’s wildfire and earthquake, and homeowner policies aren’t structured around a standardized mitigation-credit schedule for glazing. If you’re making a buying decision in Inglewood based on a promised premium reduction, you’re building on a foundation that isn’t there. That’s the plain version, and it’s better to hear it before you sign than after.
What California policies do respond to is documented risk reduction. That’s where the real conversation starts.
The Earthquake Endorsement Angle: Where the Benefit Actually Lives
Here’s the part most window companies skip. Earthquake coverage in California is typically written as a separate endorsement or through a stand-alone policy, and underwriters assess the risk profile of the structure itself. Glass-fall hazard is a recognized component of that profile. Laminated impact glazing holds together under load rather than shattering into shards, which reduces both injury risk and the interior damage an underwriter is pricing.
Some carriers and underwriters will consider documented seismic-safety improvements when evaluating that risk profile. Not all. Not on a schedule. But the conversation exists, and it’s the one worth having.
Inglewood’s specific geology reinforces it. The flats west of Prairie Avenue sit on soft soils with a long history of deferred maintenance, and plenty of those pre-1950 houses still have original single-pane glazing in aging wood frames. That’s the exact combination an underwriter looks at when assessing a quake-exposed structure. On houses like that, a permitted impact-glazing upgrade can move the needle in a way it simply won’t on a newer build near the stadium district.
Our technicians have up to 12 years of experience reading the difference between a house that needs structural attention first and one that’s ready for glazing. That assessment comes before any quote. Explore our full Windows & Doors scope to see what a permitted install includes.
What Your Insurer Actually Needs From You
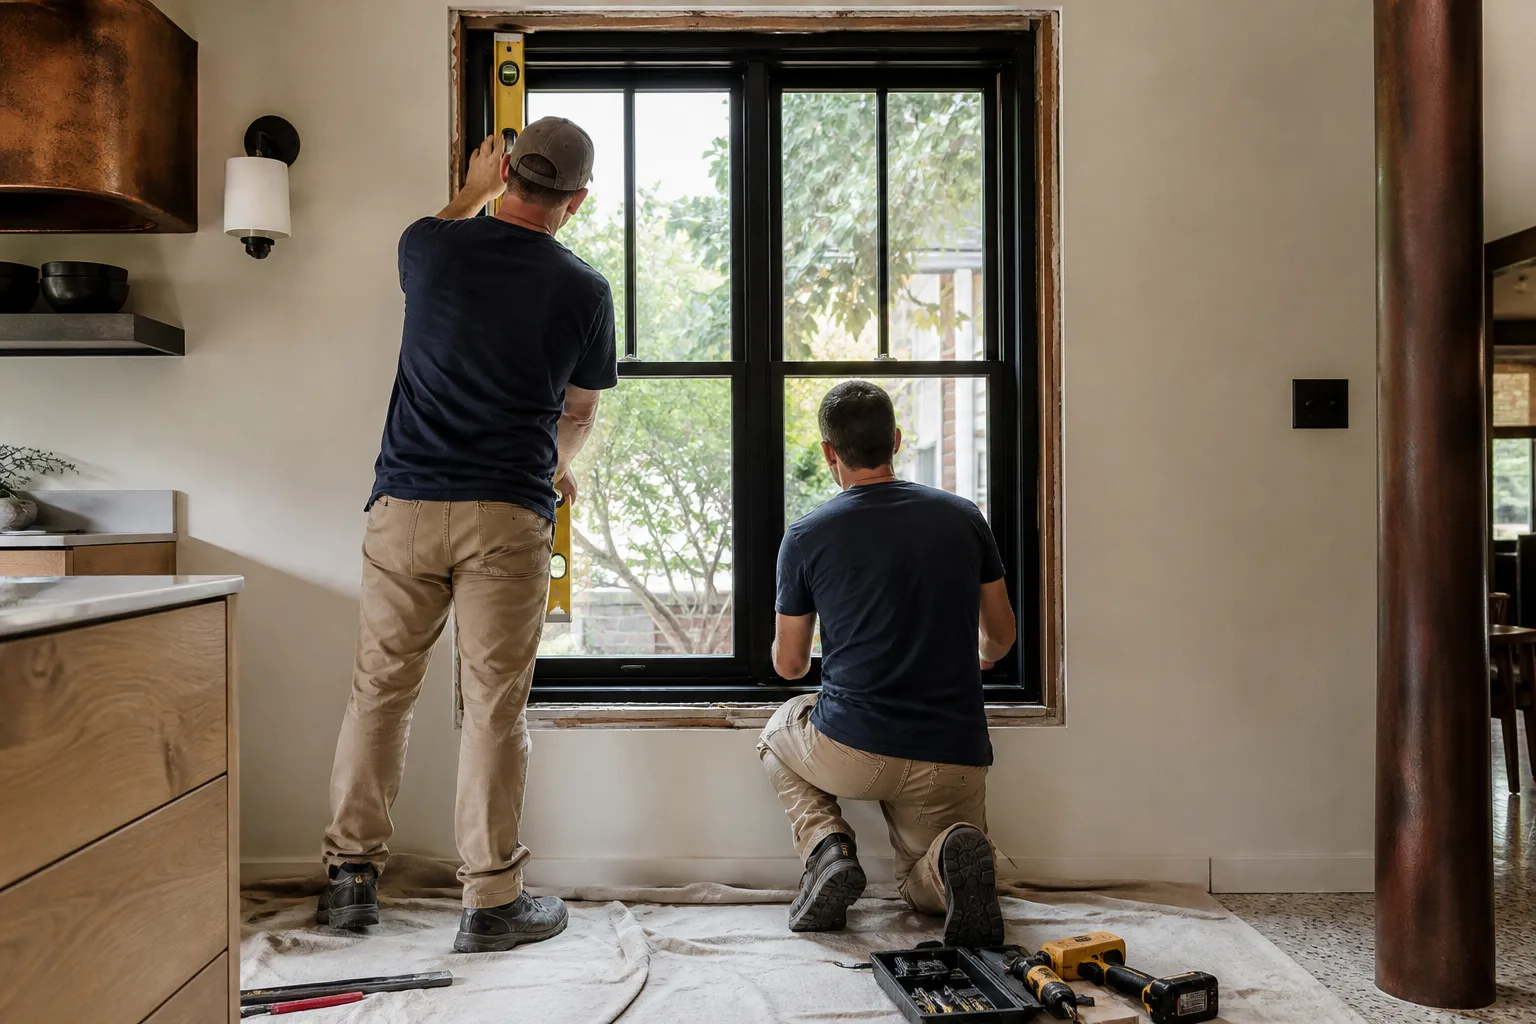
Every insurance benefit, whether it’s an earthquake endorsement adjustment or any loss-mitigation credit, rests on documentation. The path looks like this:
- A permit pulled through the City of Inglewood. Unpermitted work leaves no trail an underwriter can use.
- Inspection and a dated final sign-off. The city’s inspection record is the paper that makes the improvement legible to a carrier.
- The NFRC rating and frame specification for the exact unit installed. This is what the underwriter reviews.
- Material documentation tied to the install date. Brand, model, glazing type, and U-factor, all matched to the job.
This is where a permit-free swap costs you more than it saves. A homeowner who replaces windows through an unpermitted side job gets a nicer view and nothing else, because there’s no dated record for the carrier to recognize. The improvement happened, but it’s invisible to the people pricing your risk.
We provide complete material documentation with every Andersen and Marvin installation, including the NFRC ratings and frame specs your carrier needs. That documentation is part of the job, not an upsell.
What Impact Window Installation Costs in Inglewood
Impact window installation in Inglewood runs $8,000-$25,000 depending on the number of openings, the frame material, and whether the house needs any framing or stucco repair. Standard window replacement runs $4,500-$15,000. The gap between the two is mostly the laminated glazing and the heavier frames that hold it.
| Scope | Inglewood Range |
|---|---|
| Impact window installation | $8,000-$25,000 |
| Standard window replacement | $4,500-$15,000 |
| Roof replacement (often bundled) | $8,000-$20,000 |
| Small kitchen remodel (for scale) | $9,000-$20,000 |
Sticker price is only part of it. A permitted install that generates a clean inspection record and complete material documentation is a different product than a permit-free swap, even when the glass is identical. That paperwork is what an underwriter can act on. We quote the number once and it doesn’t move. No-hassle upfront pricing, and the number you see is the number you pay. If you’re planning a larger scope alongside the windows, the Inglewood service area page covers the full range of work we handle here.
What to Look For Before You Buy on the Insurance Premise
Most homeowners come to this question with a number in their head from a Florida blog. Here’s how to pressure-test any contractor’s pitch against reality:
- Ask for the carrier’s name and the specific credit. If a salesperson promises an insurance discount, they should be able to name the carrier and the credit program. If they can’t, the promise is fiction.
- Confirm the permit path. Ask who pulls the City of Inglewood permit and who schedules the inspection. A contractor who dodges the question is planning a permit-free install.
- Get the NFRC rating in writing before signing. You’ll need it for the carrier anyway.
- Check the warranty term against the product lifespan. Impact glazing is a 30-year decision. A warranty that expires before the glass does is a marketing number.
Every project we complete is backed by the 730-Day Done Right Promise. If it’s not done right, we make it right. On a product you’ll live with for decades, that matters more than any projected premium reduction.
FAQs
Not through a standardized discount. California homeowner policies aren’t built around the wind-mitigation credit schedules Florida uses, so there’s no standard impact-window discount here. Some carriers may factor documented seismic improvements into earthquake coverage endorsements, but that’s carrier-specific and requires documentation. Call (833) 842-7204 for an exact quote on the install itself, estimates are free.
No, because there’s nothing to accept. Insurance credits of any kind require a permitted, inspected installation with a dated City of Inglewood final inspection sign-off. A DIY swap or a permit-free install produces no documentation an underwriter can recognize, even if the glass itself is rated. Call (833) 842-7204 to talk through a permitted install.
Most residential installs are completed in a single visit, though larger jobs with framing repair may run into a second day. The permitting and inspection timeline through the City of Inglewood is the bigger variable, and it’s worth planning around given how backed up the department has been during the stadium-district build-out. Call (833) 842-7204 for a scheduling estimate.
No. The insurance benefit in Inglewood is real but indirect and carrier-specific, so it shouldn’t be the lead reason. The stronger case is seismic safety on older housing stock and 30-year durability. Treat any premium adjustment as a bonus. Call (833) 842-7204 for a free estimate and a straight read on whether your house is a good candidate.
Getting a Straight Answer on Your Specific House
If you’d rather have it looked at, Groundwork Construction Co. of Inglewood offers a no-pressure assessment in Inglewood. We’ll check the existing glazing and framing, tell you what a permitted install involves, and hand you the documentation your carrier will ask for. Call (833) 842-7204 for a free estimate.
Written by the team at Groundwork Construction Co. of Inglewood, serving Inglewood, CA.


